
Listen to the audio version of this article (generated by AI).
Editor’s Note: SmartMoney's Louis Navellier is keenly analyzing the recent convergence of dwindling job growth and softening inflation, both of which may position the Fed for a pivotal shift.
Today, Louis will break down this critical data and its implications for both Federal Reserve policy and stock market trends, revealing why he thinks the outlook may be turning increasingly positive for investors.
He also has insights on a particular sector that stands to thrive in this environment — don't miss this.
Let's set the scene: August 7, 1974, a day that would go down in history as Philippe Petit, a daring high-wire artist, executed an unprecedented act. He stepped onto a tightrope strung between the Twin Towers of the World Trade Center, balancing delicately while towering 1,350 feet above New York City. His audacious feat captivated an audience below, but the stakes were monumental.

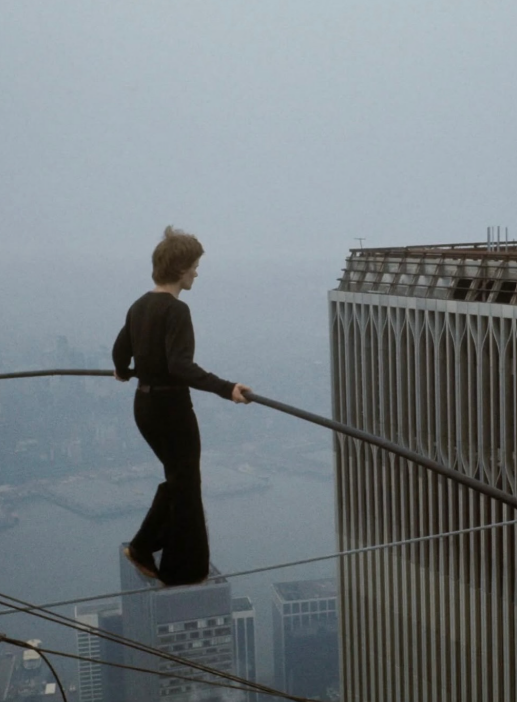
Source: twintowers_nyc / Instagram
While Petit took risks without safety gear, the Federal Reserve finds itself navigating a treacherous economic climate characterized by dual mandates: controlling inflation while fostering employment. Recent developments underscore the Fed's precarious position.
Last Friday's job report was a stark reminder of these challenges, revealing a loss of 23,000 positions within the U.S. economy. Moreover, employment figures from May and June were revised downward by an alarming 103,000 jobs.
What’s perplexing is the drop in the unemployment rate from 4.2% to 4.1%, suggesting a discrepancy as roughly a million individuals exited the labor force. The reasons behind this exodus remain unclear—possibly aging demographics or undocumented worker removals. What’s evident is that a contracting job market could deter the Fed from further rate hikes.
This week has brought renewed focus to inflation data, with the Consumer Price Index (CPI) released yesterday, followed by the Producer Price Index (PPI) today. We need to unpack these figures carefully to gauge their implications for the Fed’s strategy and stock market prospects.
A Critical Examination of Inflation Trends
The CPI report released yesterday pointed toward stability, showing consumer prices climbed a modest 0.1% in July. This resulted in a decrease in the year-on-year inflation rate to 3.4% from 3.5% recorded in June. Core inflation, which excludes volatile segments like food and energy, increased by just 0.2% for the month, leading to a year-over-year slowdown to 2.5%.
These numbers suggest a gradual easing of inflationary pressures, with particularly positive developments in shelter costs, which account for a substantial proportion of the CPI. Shelter costs experienced a minor rise of only 0.1% in July, echoing the increase from June. This signals a cooling trend in one of the critical inflation drivers—an optimistic sign for the broader economy.
Additionally, the energy sector also contributed positively, with prices falling by 1.5% due to a decrease in gasoline costs by 2.9%. Although energy prices remain elevated—up 14.7% from a year prior—the recent declines provide a buffer against inflationary woes.
However, the CPI alone offers a limited view of inflation, necessitating a closer look at the Producer Price Index for a more comprehensive understanding. The latest PPI report brought even more encouraging news, with producer prices holding steady in July when a 0.2% rise was predicted. Year-over-year increases fell to 4.7%, down from 5.5% in June.
This data, particularly the drop in goods prices by 0.7% and reductions in food (0.9%) and energy (3.1%) prices, indicates a significant cooling of inflation expectations. Collectively, these metrics suggest that inflationary pressures are substantially diminishing—an encouraging development for the Fed.
The Implications for Federal Reserve Policy
The Fed’s situation as it balances these inflation trends against job market realities is increasingly complex. While inflation appears to be receding, a weakening labor market raises questions about the impetus for further rate increases.
Concerns persist, particularly around specific components affecting the Fed’s preferred Personal Consumption Expenditures (PCE) inflation measure, hinting at potential upward adjustments that could compel the Fed to act. The disparity between the federal funds rate (currently at 3.50%-3.75%) and the two-year Treasury yield suggests some market turmoil; either rates must realign or the Fed may eventually raise its rates.
However, with the two-year yield dropping from 4.36% to around 4.14%, the markets are already experiencing a downward shift. Given the cooling inflation, I believe the Fed may not need to make any changes to rates—an outcome that could bode well for equity markets.
Shifting Focus: Where to Invest
What can investors expect moving forward? Here’s where I see significant opportunity. The S&P 500’s earnings could surge approximately 50% as the earnings season progresses, with numerous sectors showing unexpected resilience.
Notably, my focus remains sharp on artificial intelligence (AI), a sector poised for explosive growth. Companies are significantly investing in infrastructure to support AI advancements, leading to opportunities across various industries. However, with this boom comes the challenge of identifying the most viable investments amidst a surge of options.
Alongside my InvestorPlace colleagues Luke Lango and Eric Fry, we've been deep in research to pinpoint the top opportunities stemming from the AI wave. Stay tuned—next Wednesday, August 19, we're unveiling a key announcement that could help investors navigate this burgeoning landscape more effectively.
I’ll share further details during our special event aimed at redefining how you approach AI investments and aligning them with your financial goals.
Louis Navellier
Editor, Market 360
Discussion
Sign in to join the discussion.