Understanding how monetary tightening affects stock market bubbles depends on the inflation environment, revealing complex investor behaviors and valuations.
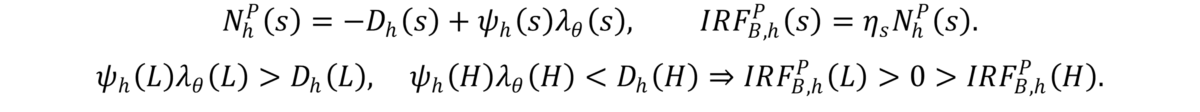
Recent research by Jamel Saadaoui, William Ginn, and Evangelos Salachas, titled Stock Price Bubbles, Inflation and Monetary Policy Surprises, investigates the nuanced relationship between monetary policy tightening and speculative equity valuations. The findings reveal that the effectiveness of contractionary monetary policy in curtailing stock market bubbles is contingent on the prevailing inflation environment.
Understanding Speculative Valuations
Identifying equity bubbles isn't straightforward given that fundamental values aren't directly observable. Building on Shiller's framework, Saadaoui's team defines bubbles as instances where stock valuations significantly diverge from traditional cash-flow and required-return metrics, primarily driven by investor psychology and market narratives. Rather than depending on a solitary indicator, their analysis uses a composite approach, primarily employing the Gao and Martin (2021) dividend-yield valuation component, which is derived from the Campbell-Shiller price-dividend model. To substantiate these findings, the research couples this with rigorous tests for explosive behavior and state-dependent valuation frameworks.
Impact of Monetary Surprises
The conventional wisdom suggests that contractionary surprises in monetary policy typically raise required returns, tighten credit, weaken demand for equities, and decrease the present value of anticipated cash flows. However, the research uncovers that these outcomes can vary wildly depending on the inflation setting at the time of the policy action. Specifically, in low-inflation climates, pre-emptive tightening may be interpreted positively, serving as a safeguard against future policy errors and expectations of more severe future tightening cycles.
Interestingly, this context may narrow risk spreads, maintain favorable cash flow trajectories, and temper the adverse effects typically associated with higher current and projected policy rates. The asymmetry in response to monetary tightening can be boiled down to two core elements: the direct valuation drag of higher rates and an upward revision in market perceptions regarding future central bank decisions and policy error risk.
Inflation Environment as a Determinant
In stark contrast, a high-inflation environment alters the response to contractionary surprises. Expectations of tighter credit conditions and higher required returns generally overshadow potential benefits, leading to reduced speculative valuations. The paper illustrates how in such circumstances, tightening actions can amplify real interest rates and fear of extended monetary restraints, discouraging risk-taking behavior and contributing to a potential deflation of previously inflated prices.
Moreover, the research emphasizes the role of heterogeneous investor beliefs in shaping market reactions. Optimistic investors might attribute favorable policy signals to improved future economic resilience, while pessimistic investors focus on increased discount rates. This divergence complicates the way market prices incorporate such policy adjustments, particularly when negative sentiment cannot manifest through short-selling.
Empirical Findings and Observations
The researchers conducted a thorough empirical analysis employing various benchmarks, including the Bauer-Swanson (BSMP) and Jarociński-Karadi (JKMP) measures of monetary policy surprises. Their findings indicate a notable reversal of signs depending on the inflation context. Specifically, contractionary policy surprises tend to narrow the BAA corporate-Treasury spread and elevate speculative valuation components in low-inflation environments, while the opposite holds true in high-inflation scenarios.
Interestingly, the authors underscore that data from the Jarociński-Karadi information shock, alongside the broader Federal Open Market Committee (FOMC) monetary-event surprise, yields a nuanced, inflation-dependent response pattern. Favorable news in a low-inflation context correlates with narrower credit spreads and upward valuation shifts but elicits negligible or negative responses in high-inflation climates.
Reconciling Contradictory Perspectives
The research effectively bridges two prevailing theories in monetary economics regarding the interaction of policy actions and speculative bubbles. The traditional view posits that tighter monetary policy raises required returns and restricts credit, leading to reduced speculative valuations primarily in high-inflation contexts. Conversely, other scholars, including Galí and Gambetti, suggest that tightening can escalate the bubble component during low-inflation phases. The current analysis reaffirms that the context of inflation plays a determining role, with contractionary surprises potentially fostering both credit accessibility and speculative buying in low inflation, while imposing stricter credit conditions and limiting speculations in high inflation.
Policy Implications and Future Considerations
This research carries significant implications for policymakers. It suggests that the interest rate cannot be treated as a blanket tool for ensuring financial stability. In high-inflation contexts, tightening aligns objectives of price stability with financial stability, tightening credit accesses and limiting speculative excesses. Conversely, in stable inflationary environments, similar policy moves may paradoxically improve credit conditions and elevate speculative investor behavior, presenting a complex picture for financial stability assessments.
When evaluating monetary policy's potential to mitigate asset price bubbles, it's essential for financial analysts and decision-makers to consider the prevailing inflation conditions and investor psychology shaping market responses. This nuanced understanding could be key in predicting future market dynamics as monetary policies evolve in response to shifting economic landscapes.
Selected references
Acosta, M., et al. (2025), “Financial Market Effects of FOMC Communication: Evidence from a New Event-Study Database,” Federal Reserve Bank of San Francisco Working Paper 2025-30.
Bauer, M. D., and E. T. Swanson (2023), “A Reassessment of Monetary Policy Surprises and High-Frequency Identification,” NBER Macroeconomics Annual, 37(1), 87-155.
Galí, J., and L. Gambetti (2015), “The Effects of Monetary Policy on Stock Market Bubbles: Some Evidence,” American Economic Journal: Macroeconomics, 7(1), 233-257.
Gao, C., and I. W. Martin (2021), “Volatility, Valuation Ratios, and Bubbles: An Empirical Measure of Market Sentiment,” Journal of Finance, 76(6), 3211-3254.
Jarociński, M., and P. Karadi (2020), “Deconstructing Monetary Policy Surprises: The Role of Information Shocks,” American Economic Journal: Macroeconomics, 12(2), 1-43.
Phillips, P. C. B., et al. (2015), “Testing for Multiple Bubbles: Limit Theory of Real-Time Detectors,” International Economic Review, 56(4), 1079-1134.
Shiller, R. J. (2015), Irrational Exuberance, revised and expanded third edition, Princeton University Press.
Discussion
Sign in to join the discussion.