Senior care claim payments are rising, while excess coverage costs more and operators weigh risk controls, technology and alternative financing.
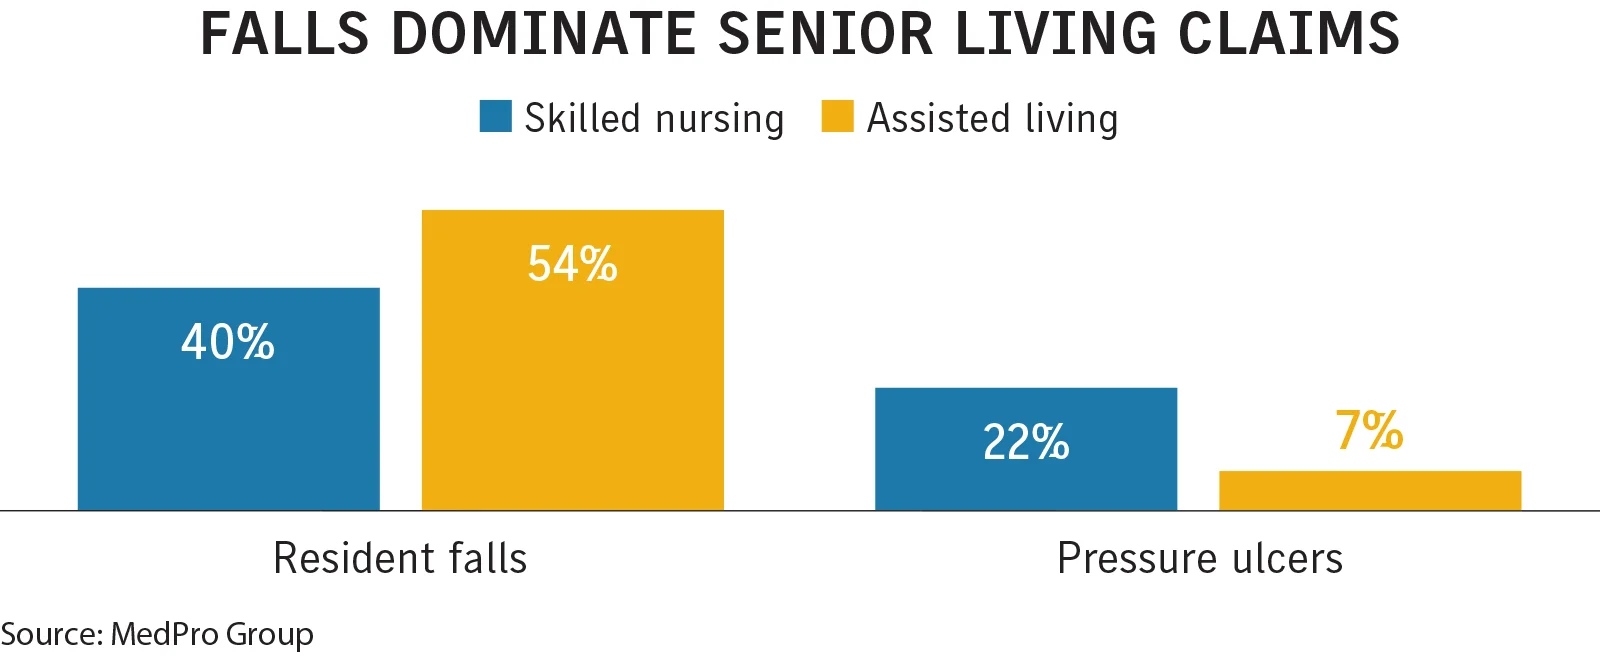
Senior living operators face a widening gap between the cost of liability claims and the availability of affordable insurance capacity. Claim severity has climbed since 2023, while excess and umbrella coverage is drawing double-digit increases and lower limits. The pressure is prompting operators to reassess how much risk they retain and how they document resident care.
Primary general and professional liability coverage remains more accessible for operators with favorable loss records and strong risk management, particularly outside difficult litigation venues. But that stability varies by location and doesn’t extend evenly across larger insurance towers. For some operators, maintaining coverage at current limits is becoming a more expensive choice.
Severity is climbing across claim sizes
Falls and pressure injuries remain common sources of senior care claims. Allegations involving abuse or residents leaving a facility unsupervised are less frequent, but can lead to especially severe losses, industry sources say.

After a short post-pandemic lull, claim severity rose sharply from 2023, according to Blaine Thomas, CNA’s vice president and global health care technical underwriting and product development leader. Medical inflation and litigation factors, including large jury awards, are adding to claim costs.
The increase isn’t limited to headline verdicts. Thomas said claims that once settled for about $175,000 can now reach $500,000, creating a significant expense burden for the sector. MedPro Group’s July report found that average indemnity payments on senior care claims rose to $253,000 in 2024, up from $179,000 in 2019.
Memory care exposure can add to the cost. In MedPro’s analysis of more than 2,000 claims nationally, the average indemnity payment for memory care cases in assisted living facilities was $233,000, nearly 23% above the average for assisted living cases without memory care exposure.

Recent jury awards illustrate the potential scale of severe cases. A Sacramento County jury awarded $110 million in a case involving a 100-year-old resident with Alzheimer’s dementia who wandered outside a senior living facility and died of hypothermia. The award included $100 million in punitive damages. DigitalBridge Group, formerly Colony Capital and a defendant, said in an Aug. 4 SEC filing that it disagreed with the verdict and intended to appeal any judgment and pursue post-trial remedies.
In July, a federal jury in Montana awarded nearly $16 million to the families of two residents of a Billings memory care and assisted living facility in a case alleging negligent care. The award included $15.5 million in punitive damages. Koelsch Senior Communities is seeking to reduce the punitive damages through post-trial motions.
These cases can be difficult to defend because allegations of neglect or abuse involving vulnerable residents may resonate strongly with jurors, said William J. Mundy, a health care defense attorney at Burns White. Unlike many bodily injury cases, senior living claims often don’t center on lost wages or future medical costs. Plaintiffs may instead emphasize dignity and the emotional impact of alleged mistreatment. That can raise claim values even when the financial losses are less conventional.
Excess coverage costs more and offers less capacity
Excess and umbrella liability markets are under greater strain than primary coverage. Insurers are restricting capacity and seeking higher prices, particularly for large accounts. Rate increases can reach 30% or more depending on the size of the tower and where its capacity is placed, said Scott Wallace, Marsh Risk’s managing director for senior living and long-term care.
Benchmark Senior Living saw excess liability costs rise about 20% at its latest renewal, according to Rachel Thuerk, the company’s vice president of risk management. Its primary liability program has remained relatively stable. The Waltham, Massachusetts-based operator runs 72 communities across nine states, from Virginia to Maine, and largely avoids venues considered especially difficult for liability coverage, including California, Cook County, Illinois, and Philadelphia.
Thuerk said capacity is still available, but another 20% to 25% annual increase could lead Benchmark to reconsider the size of its insurance tower. The company is studying whether a captive could help fund retained workers compensation losses, with other lines potentially considered later.
Insurers that once offered individual excess limits of $10 million, and sometimes $15 million, have generally reduced those limits to $5 million, Wallace said. Building a $20 million tower may now require three or four insurers. Jack Harms, an assistant vice president and broker at CRC, said carriers may be comfortable offering $5 million but become less willing to deploy $10 million or more.
Coverage terms also need close review as policies stack. Abuse coverage may be available, but an excess policy might not follow an abuse sublimit in the primary policy. Harms said that mismatch can leave an operator without abuse coverage through the full tower even when the excess policy appears to include it.
Primary pricing is generally flat to up single digits for operators with good loss experience in more favorable jurisdictions, said Alex Whipple, a senior vice president in CAC’s senior living practice. California remains difficult: an operator with a favorable loss ratio and a $100,000 retention could face a $250,000 retention or a substantial rate increase. Some smaller and mid-sized operators in markets such as California are dropping excess coverage because of the cost, while larger operators generally continue to buy it.
Los Angeles and Sacramento counties remain among the toughest venues, Whipple said, alongside Cook County, Florida and Georgia. CNA’s Thomas said primary claim severity has compounded at about 10%, while rate increases since 2023 have lagged that trend. In his view, pricing has not caught up with the claims experience.
Risk controls and technology carry both benefits and obligations
Operators are using technology to reduce incidents and improve records, but a system that documents a successful response can also capture a failure to act. Benchmark has tested SafelyYou, an AI-powered camera system that detects falls in several memory care communities. Thuerk said footage can help staff establish whether a resident hit their head, lowered themselves to the floor or recovered without assistance, and decide whether an emergency room transfer is appropriate.
Benchmark has also expanded hands-on staff training in wheelchair securement, elopement prevention, chemical security and fire safety. Thuerk said in-person practice is more likely to stick than a video employees click through to complete a training requirement.
MedPro found that staffing, protocol adherence and communication issues appeared more often in paid senior living claims of $500,000 or more. Insurers are also examining ownership and management histories, including private equity involvement and repeated facility sales. Dan Gilhooly, a managing director at Arthur J. Gallagher & Co., said underwriters want to know who operates facilities, how long owners have been involved and who makes operating decisions. Frequent changes can raise questions about leadership and staffing stability; investment may be viewed positively when it brings experienced ownership and added resources.
Technology adoption is increasing. LifeLoop reported that 37% of industry professionals used AI-powered tools in 2025, compared with 9% in 2024.

Monitoring systems can record when staff respond to alerts, helping operators document care and defend claims, Thomas said. The same record can expose a delayed or inadequate response. Electronic medication administration records can also flag incomplete documentation before a shift ends, Mundy said. Call-bell audits may show response times; an eight-to-10-minute wait, compared with an industry average of about five minutes or less, could become an issue in a claim.
Insurers have been slow to translate loss-prevention technology into direct premium discounts, said Carl Swan, an executive vice president in CAC’s senior living practice. Larger programs may instead receive risk management grants of $25,000 to $50,000 for fall prevention, wound care or predictive analytics.
Risk retention is becoming part of the insurance strategy
As claims costs rise and commercial capacity tightens, operators are exploring captives and risk retention groups. PCH Mutual, a Vermont-based risk retention group formed in 2004, serves small and midsize nonmedical residential care facilities. It operates in 47 states, typically offering $1 million per occurrence and $3 million aggregate limits, including sexual and physical abuse coverage. CEO Julie Bordo said the group also provides members with care documentation software and other risk management resources at no cost.
Marsh Agency launched Secure Harbor in January, a group captive offering general and professional liability coverage to skilled nursing, assisted living and senior living facilities. Domiciled in Washington, D.C., it offers limits up to $1 million per occurrence and $3 million aggregate to businesses with similar risk profiles, along with claims administration and safety consulting services.
Risk retention has spread across the sector. Thomas estimated that about 90% of senior living insurance premium is now connected to a deductible or self-insured retention, compared with a market once dominated by first-dollar coverage. Some larger operators use captives to fund retained claims, while others build insurance towers or retain more risk because market pricing makes coverage unaffordable.
For senior living operators, the immediate financial test is whether coverage limits, retentions and documented operating practices match the risks they can absorb. As severity outpaces primary rate adjustments and excess capacity costs more, the quality of staffing, protocols and records will increasingly shape both claim outcomes and renewal terms.
Discussion
Sign in to join the discussion.