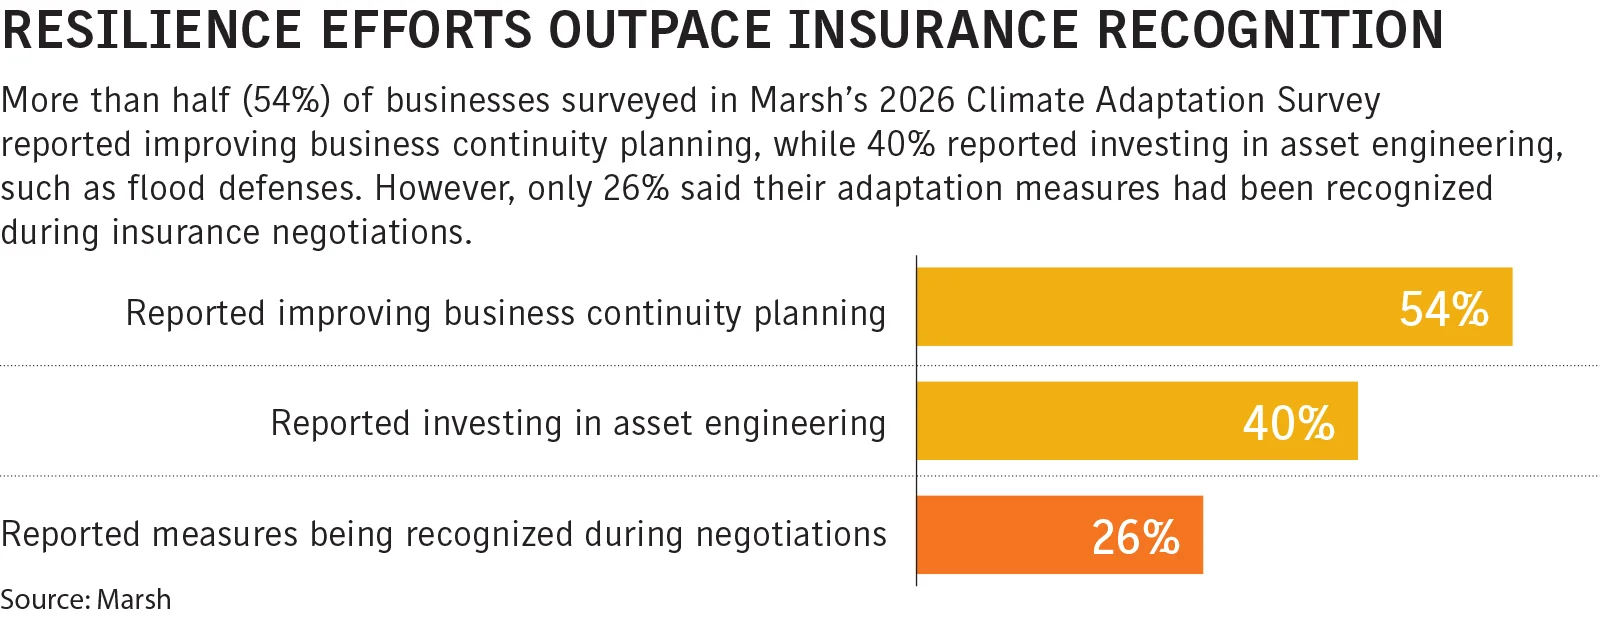
Resilience investments can attract insurance capacity and improve terms, though only 26% of surveyed organizations said insurers recognized their adaptation work.
Property resilience can strengthen an owner’s position in insurance negotiations, but the payoff often comes through added capacity and better terms rather than a credit tied to a single upgrade. That distinction matters in a competitive market: insurers may favor better-prepared risks without consistently measuring each investment or reducing premiums by a set amount.
“It’s not a direct correlation to a premium reduction for doing that one thing,” said Blake Giannisis, New York-based executive vice president and North American property practice leader at Hub International. A stronger risk profile can draw more capacity, he said, and competition among insurers may then help lower costs.
Recognition still appears limited. In Marsh’s 2026 Climate Adaptation Survey, released in September, only 26% of more than 120 organizations worldwide said their adaptation efforts had been recognized during insurance negotiations.

Investments can strengthen the negotiating position
Prologis has raised construction standards for its developments, extending the expected life of some roofs from 20 years to 30, said Jeff Bray, the San Francisco-based logistics real estate company’s senior vice president and head of global risk management. “We are using products that are intended for a longer, more durable life cycle,” he said.
The company owns and develops about 6,000 properties across 20 countries. In some years, it has also voluntarily spent millions of dollars retrofitting properties exposed to earthquakes, with the aim of reducing damage and disruption to customers, Bray said.
He could not identify direct premium savings across the portfolio from the seismic work. But resilience spending can distinguish Prologis in underwriter discussions and support negotiations over capacity, deductibles and coverage terms. Bray described the investments as “a strong signaling tool” that shows insurers the company is reinvesting in its properties and “becoming a better risk.”
Operational planning also comes up in those discussions. Prologis raises disaster response and backup power plans with insurers, Bray said, but carriers do not consistently record those steps as data points. Earlier this year, the Risk & Insurance Management Society named him its 2026 Risk Manager of the Year.
For Raymond Chiusano, New York-based head of property for AXA XL’s East zone, resilience has value in both soft and hard markets. Prepared businesses may prevent or limit losses, recover faster and reduce downtime. Over time, those characteristics may also help them secure steadier capacity, he said.
Insurers and risk engineers work with policyholders to assess changing exposures and plan responses, Chiusano said. Measures can include physical improvements to facilities, emergency procedures and disaster recovery plans. Health care organizations often focus on preventing and responding to water losses. Life sciences companies and manufacturers can address supply chain exposure by vetting suppliers, finding alternative sources and holding buffer inventory.
For property owners, leak sensors and water flow monitoring can flag unusual use and help prevent damage. “If an insured is proactive with those items of resilience, I’m more willing to put out more capacity,” Chiusano said.
Measurement remains a hurdle
Insurers’ ability to reflect mitigation in pricing depends partly on what their catastrophe models and other risk tools can measure. Existing models can account for some property features, but community-wide work may be harder to quantify, said Kim Roberts, Fort Collins, Colorado-based head of North America peril advisory at Marsh Re.
“We need to be able to speak the language of reinsurance and insurance, and translate these actions into measurable metrics,” Roberts said at a Marsh-sponsored panel during Climate Week NYC in September.
A California wildfire policy offers one example of resilience translating into improved terms. Last year, The Nature Conservancy and Willis Towers Watson developed a $2.5 million policy for the Tahoe Donner homeowners association. A specialty managing general agent assessed risk reductions from forest management, including tree thinning and prescribed burns. According to Deborah Glaser, Los Angeles-based project director for disaster resilience at The Nature Conservancy, the resulting policy had a premium 39% lower and a deductible 84% lower than it would have had without that work.
Catastrophe models can account for many property-level measures when they receive detailed building data, said Glen Daraskevich, executive vice president at Boston-based modeler Karen Clark & Co. Depending on the hazard, inputs can include roof covering, glass type and building elevation. Models can use those details in estimates ranging from expected losses to probable maximum losses.
The information has to travel from risk managers to insurers and then into the models, Daraskevich said. New mitigation features can be missed when models aren’t updated often enough. Some models can also reflect community flood and wildfire mitigation if the underlying data is available.
Multiple measures can materially change modeled losses. Their combined effect can reach double digits, Daraskevich said, though the result depends on the hazard and other conditions. For owners and insurers, the practical challenge is making resilience visible in the data that informs underwriting.
Gavin Souter contributed to this report.
Discussion
Sign in to join the discussion.