Companies are testing event contracts to offset supply chain and weather exposures, while liquidity and payout reliability remain open questions.
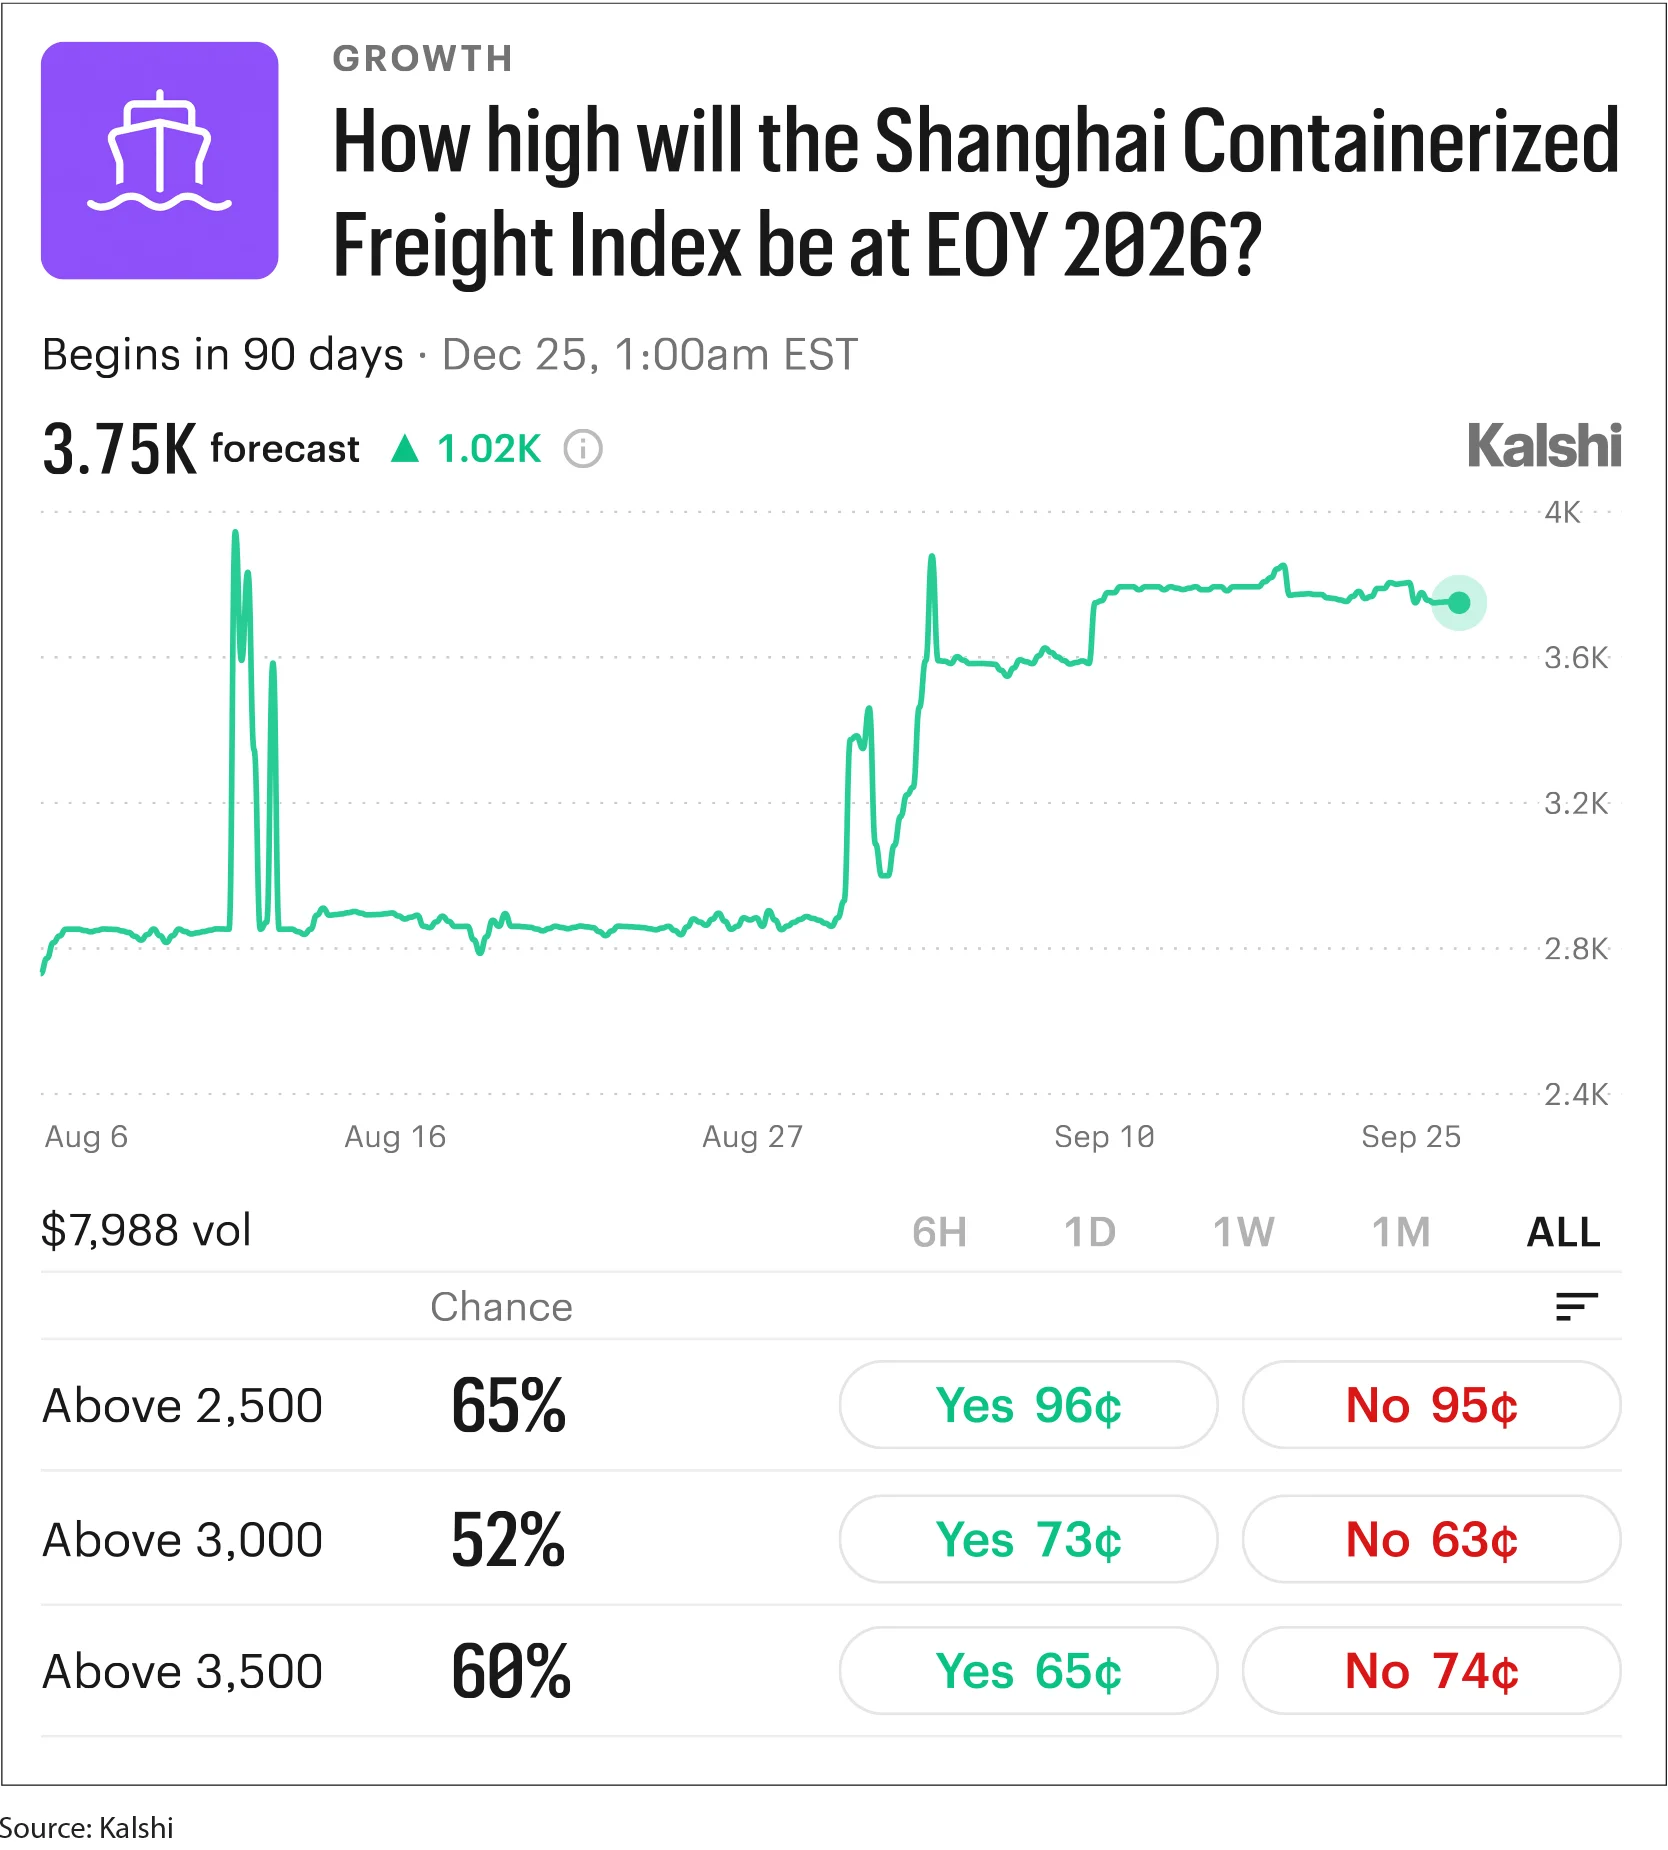
Prediction markets are beginning to serve as a practical hedge for businesses facing costs that conventional insurance and derivatives may not cover. Their appeal is speed and flexibility: companies can take positions as risks develop, including around freight costs, tariffs and local weather. The trade-off is that a contract’s payout may not track a company’s actual loss, and market depth and reliability remain unresolved.
Small firms test targeted hedges
James Fayal, whose Baltimore-based company Zest sells Asian tea worldwide, has used Kalshi contracts to address two sources of volatility: tariffs and shipping. A successful position on the prospect of President Donald Trump imposing a tariff on Canada paid out after the tariff was levied, offsetting part of the lost sales tied to a Canadian customer.
Fayal also worked with Kalshi over the summer to create a contract linked to a Shanghai shipping index. The contract pays if container shipping costs clear specified thresholds, giving Zest a potential offset when freight expenses rise. The structure points to a gap in conventional hedging: large companies can arrange forward contracts across many shipments, while smaller importers may lack access to comparable arrangements.
“If I were Procter & Gamble, I would be setting up forward contracts on a thousand containers” to lock in shipping costs, Fayal said. “That’s not something that is readily available to me as a small business owner.”
Other businesses are trying event contracts against operational exposures. Kalshi users include a kayak tourism operator seeking protection from rain-related cancellations, an ice cream shop owner betting against cold days that could weaken sales, and an online farmers market hedging extreme heat that could damage crops. These examples are narrow by design: each business is trying to connect a defined event to a recurring source of revenue risk.
Event contracts bring a different timing
Kalshi contracts resolve to either $1 or $0 depending on whether a specified event occurs. A correct prediction earns the difference between the contract’s purchase price and its $1 settlement value, less fees. An incorrect prediction loses the amount invested. Traders can also sell before the event is settled.
Founded in 2018 by Tarek Mansour and Luana Lopes Lara, Kalshi grew from an effort to let users trade directly on real-world events. Mansour had previously worked on derivatives for clients seeking protection from the 2016 Brexit vote, according to Nicolas Hull, Kalshi’s head of business development. The platform now covers areas including politics, commodities, economics and finance, alongside its better-known sports-related markets.
Kalshi has also added negotiated block trades for eligible contract participants. These transactions currently require at least 25,000 contracts. The company’s handbook outlines potential uses across real estate, retail, health care and other sectors, though the minimum size and eligibility rules put the product beyond many smaller firms.
ForecastEx, operated by Interactive Brokers in Greenwich, Connecticut, offers contracts tied to severe and ordinary weather. Patrick Brown, the firm’s head of climate analytics, describes the structure as more straightforward than traditional weather derivatives and says it can support more efficient price discovery than parametric insurance.
Weather contracts can be traded as a storm approaches. ForecastEx offers positions tied to wind gusts within a 10-kilometer radius of dozens of U.S. population centers. A business exposed to a storm could use a successful position to help meet its property insurance retention, Brown said. The timing may suit companies better than coverage priced months before the relevant weather conditions emerge.
Market signals can inform risk decisions
Robert Hartwig, director of the Risk and Uncertainty Management Center at the University of South Carolina, sees real-time pricing as one potential advantage. Insurers typically set rates well before a covered period begins, while an event market can shift as new information arrives.
Hartwig described taking a large deductible on wind coverage for his home and, as a classroom exercise, placing a successful Kalshi position on hurricane activity being below normal that season because of El Niño. “I had more information than (insurers) did as we approached the actual hurricane season,” he said. His example illustrates the appeal of updating a risk view closer to the event, though it does not establish that such a position would reliably offset an insured loss for a business.
Market prices may also be useful even when a company does not trade. Michael Gruetzmacher, Aon’s head of alternative risk, said corporate risk managers could consult prediction markets for feedback on significant events that are difficult to insure, including the outcome of midterm elections. That information could inform internal planning without serving as a direct financial hedge.
Tom Markovic, Marsh’s global head of parametric solutions, said insurers often avoid regulatory, legal and supply chain exposures because they can be systemic or hard to model. Prediction markets may draw in capital market participants, including hedge funds seeking returns, and could create another source of capacity for some risks. The extent of that capacity will depend on whether trading remains deep enough to support meaningful positions.
Basis risk and market confidence remain hurdles
The main financial mismatch is basis risk: a contract can settle as written while a company’s actual loss differs in size or direction. A broad economic event, such as higher interest rates, may affect individual businesses in different ways. Rob Hoyt, a risk management professor at the University of Georgia, said it can be difficult to translate such an event into a specific company’s financial impact. Insurers, by contrast, build their business around estimating losses from adverse events.
Questions about liquidity and market reliability also matter. A business needs to know that it can establish or exit a position at a usable price, and that the contract’s settlement process will produce a dependable outcome. Those concerns have become more visible as Kalshi and Polymarket have faced allegations of insider trading and manipulation.
Kalshi has canceled contracts after disputes over ambiguous wording, including markets concerning the duration of a 2026 government shutdown, the timing of the death of Iran’s Ayatollah Ali Khamenei, and rapper Cardi B’s appearance at the Super Bowl. Polymarket has drawn criticism over the reliability of its UMA dispute process. Several states have also sought to shut down Kalshi, arguing that it operates as a sports betting site requiring a gaming license.
That uncertainty sits uneasily alongside the certainty businesses expect from insurance, where regulators and credit agencies provide assurances about insurer stability. Nick Martin, Alliant’s alternative risk transfer lead in Atlanta, framed the core concern: “The whole idea of insurance is to provide financial certainty. Do you feel certain payments will be received, or that you will satisfy your downside, with these types of solutions?”
For companies with exposures that standard policies and hedging tools leave open, event contracts may offer a useful additional instrument, particularly when risks are specific and observable. Their role will depend on whether the contract tracks the company’s actual loss and whether the market can deliver a dependable payout when conditions turn adverse.
Discussion
Sign in to join the discussion.