Alternative capital has reached $145 billion, with cat bonds moving lower in some towers and sidecars opening paths into liability reinsurance.
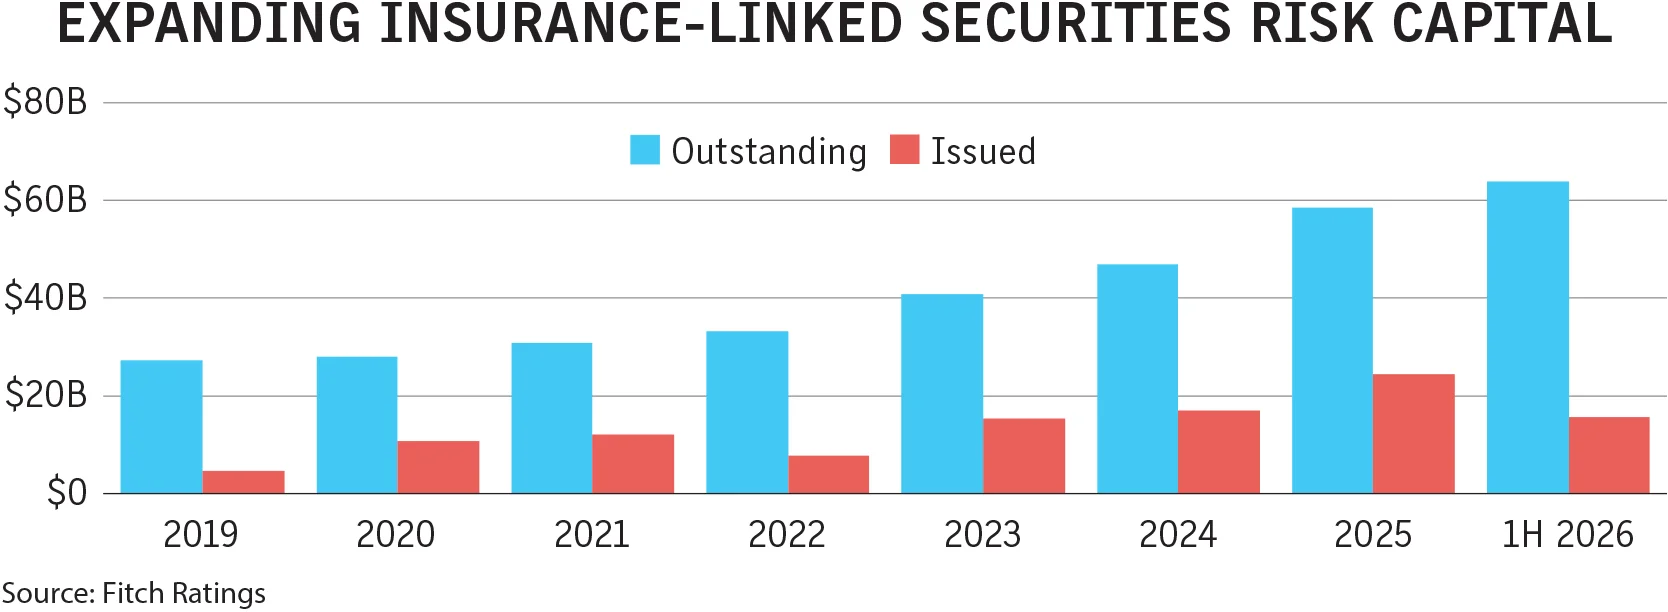
Alternative reinsurance capital has reached $145 billion, and its role is beginning to widen beyond property catastrophe coverage. The next test is liability reinsurance: investors and cedents are exploring casualty structures, even as long claim timelines bring more demanding questions about reserves, liquidity and the time capital must remain committed.
Richard Pennay, CEO of Aon Securities, Aon’s insurance-linked securities business, puts the market at $145 billion, or about 18% of total reinsurance capital. It grew at an average annual rate of 6.5% over the past decade and 13.5% over the past three years, he said. That expansion is giving buyers more ways to secure capacity, but the market’s center of gravity remains property catastrophe risk.

More capacity, and a different source of competition
Catastrophe bonds and other alternative structures have typically covered remote, severe events near the top of reinsurance towers. U.S. named windstorm and hurricanes are among the risks they commonly take on. Terry McLean, president and CEO of SageSure, said cat bonds historically sat almost exclusively in that upper layer through Rule 144A catastrophe bonds. With capital flowing into the market and spreads compressing over the past year, he said, some bonds are now attaching lower in towers.
That shift matters to cedents building a reinsurance program. Alternative capital gives buyers access to investors whose capacity responds to different market dynamics than traditional reinsurers, said Laurent Rousseau, CEO of global capital and advisory and head of international at Marsh Re. The additional source can bring more competition to placements and, in some cases, help buyers manage the effects of geographic concentration limits imposed by traditional reinsurers.
For buyers, the value is broader than price alone. Niraj Patel, head of alternative capital for Axa XL, said a deeper pool of capital can create price efficiencies and diversify counterparty exposure. Mitchell Rosenberg, co-head of global ILS at Howden Capital Markets & Advisory, described the central benefit as optionality: more ways to finance and transfer risk. That can support capacity and pricing through different phases of the reinsurance cycle, though the terms and performance of any structure depend on the specific risk and contract.
Alternative capital has grown to a scale where it can absorb up to 20% across reinsurance placements and renew, Rousseau said. In some parts of the United States, Aon has seen cedents place more than 25% of their total reinsurance purchase through catastrophe bonds, Pennay said. Zach Breslin, capital markets leader for Lockton Re Capital Markets, said the supply gives buyers another way to introduce competitive pressure into their purchasing programs.
Multi-year cover can steady annual renewals
Catastrophe bonds can offer multi-year coverage, with some buyers locking in three or four years of protection. That duration can reduce the amount of a program that must be renegotiated each year and make part of the cost and capacity less exposed to annual market swings.
Breslin said multi-year placements can dampen volatility in annual results by fixing some pricing and capacity for several years. Jason Bolding, CEO of Gallagher Securities, Gallagher Re’s ILS division, said a cedent with a large cat bond in place may need to buy less additional limit to complete its reinsurance tower. The effect is practical: a portion of the program is already covered before the annual renewal, leaving a smaller remaining requirement to place.
That certainty comes with trade-offs. Cat bonds and collateralized covers require investors to post collateral in advance. If a major event produces claims that take months or years to assess, some of that money can remain tied up beyond the contract term. Investors may then be unable to redeploy it while the loss picture develops.
Claims timing remains a structural constraint
The experience after hurricanes Harvey, Irma and Maria in 2017 left some investors waiting for losses to be resolved before they could use their capital again. Similar concerns followed Hurricane Ian in late 2022. McLean said cat bonds and collateralized covers can face extension periods and trapped collateral when loss estimates take a long time to develop, a friction he said does not arise in the same way under traditional unsecured treaties.
Bolding said trapped capital is an enduring possibility because losses take time to crystallize. Its importance depends partly on how quickly claims can be assessed and settled. Series 144A catastrophe bonds, which account for most of the market, use predetermined claims processes intended to limit disputes, Breslin said. Independent third parties oversee the structured recovery process, he added, creating transparency around claims and payment.
Casualty growth brings a longer investment horizon
Investors are also looking beyond property catastrophe risks. Pennay said the past 18 to 24 months have brought a notable expansion of sidecars, including whole-account and casualty-based structures. Bolding said more cedents are considering alternative capital for casualty business.
The opportunity is real, but liability risks behave differently from catastrophe exposures. A.M. Best said in a September report that liability losses can take years to emerge and may be affected by shifts in the legal and social environment, leaving uncertainty around ultimate costs. Investors therefore need to account for reserves and the length of time their collateral may be tied up.
Patel said longer-tail lines require investment modeling that reflects how long risk collateral may be held. Rosenberg likewise pointed to greater reserving, duration and liquidity considerations in casualty and other long-tail business. Those features make it harder to apply the property catastrophe model directly: a structure built around a defined event and relatively remote loss may not fit risks whose claims develop gradually.
The market’s next phase will depend on whether structures can make those longer obligations clear enough for investors while meeting cedents’ needs for dependable capacity. Property catastrophe remains the foundation, but the expansion of casualty sidecars shows where participants are testing demand. The key measure of progress will be whether alternative capital can provide liability capacity without leaving investors uncertain about the duration and availability of their collateral.
Discussion
Sign in to join the discussion.